 July 24, 2026
A company doesn’t have to say “we’re the government” to create that impression — a mailer’s design, a caller’s script, or a website’s branding can do it just as effectively. That’s the core issue in the FTC’s Superior Servicing case, a student-loan debt-relief scheme that ended in permanent industry bans and a $45.9 million judgment.
What Happened.
The FTC sued Nevada-based Superior Servicing LLC and operator Dennise Merdjanian in November 2024, alleging the company sent personalized mailers and made telemarketing calls that led borrowers to believe they were dealing with the Department of Education or an approved loan servicer. According to the complaint, some representatives even told borrowers to stop paying their actual loan servicers — advice that damaged their credit while doing nothing to reduce their debt — while charging upfront fees of up to $899 and monthly payments the company falsely claimed were going toward loan balances. At most, the FTC found, the defendants filled out basic income-driven repayment applications that are free directly through the Department of Education.
The FTC later added five more corporate entities and two individuals, Eric Caldwell and David Hernandez, in a 2025 amended complaint. Caldwell and Hernandez settled in September 2025 with permanent debt-relief bans; Caldwell was also barred from telemarketing entirely, and Hernandez was barred from violating the Telemarketing Sales Rule. Merdjanian settled in February 2026 with a permanent ban from debt relief and telemarketing and a $45.9 million judgment, partially suspended due to her financial condition. The remaining corporate defendants were resolved through a default order in June 2026.
Why this Matters Beyond Debt Relief.
The FTC alleged violations of the Impersonation Rule, Telemarketing Sales Rule, FTC Act, and Gramm-Leach-Bliley Act — laws specific to this industry. But the underlying lesson applies to any business using mailers, lead generation, telemarketing, or affiliate marketing: consumers experience your business name, logo, phrasing, and caller identity as one combined impression, not as isolated legal claims to be checked off individually. A business can technically avoid ever saying “we’re affiliated with [trusted entity]” while still creating exactly that impression through design and word choice — and a misleading first impression at the mailer or ad stage can taint everything that follows, even if the sales script itself is technically compliant.
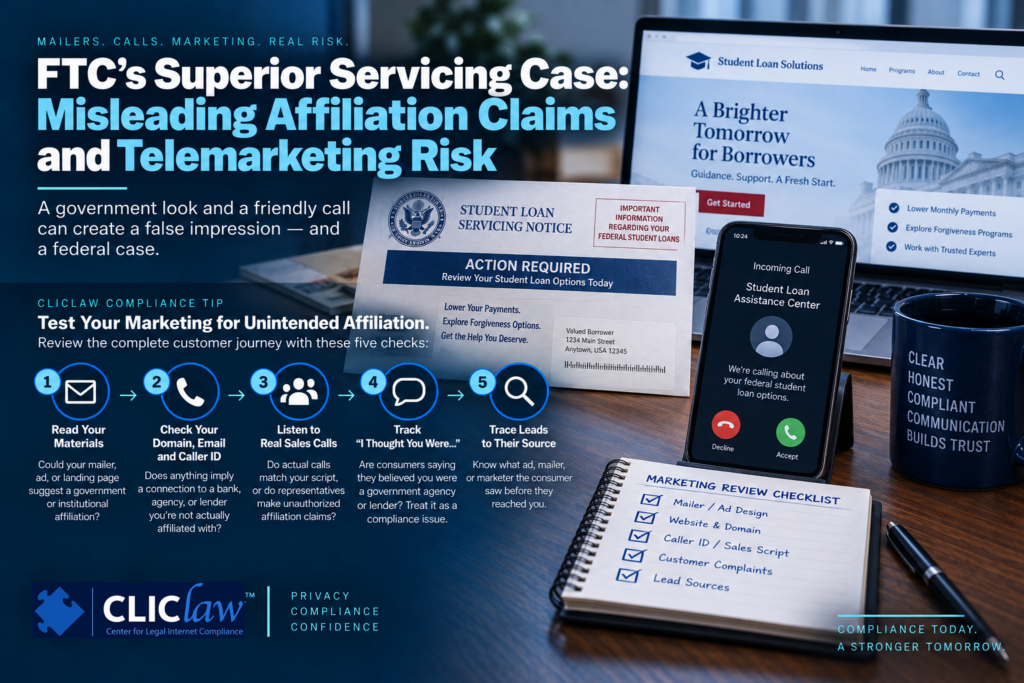
CLIClaw Compliance Tip: Test Your Marketing for Unintended Affiliation.
Before launching or continuing a lead-generation, direct mail, or telemarketing campaign, review the complete customer journey for identity clarity:
-
Read your materials as a first-time recipient. Look at your mailer, ad, landing page, and caller ID together — do words like “Official Notice,” “Benefits Department,” “Federal Program,” or seals/logos suggest a government or institutional affiliation you don’t actually have?
-
Check your domain, email, and caller ID. Does anything about how you present your business online or by phone imply a connection to a bank, agency, lender, or other trusted entity you’re not actually affiliated with?
-
Listen to real sales calls, not just the approved script. A compliant written script means little if representatives deviate from it — spot-check actual calls for unauthorized affiliation claims or unsupported promises.
-
Track the phrase “I thought you were…” in complaints. If customers repeatedly say they believed they were dealing with a government agency, their lender, or another trusted party, that’s a signal your marketing is creating a false impression — treat it as a compliance issue, not just a customer-service note.
-
Trace leads back to their source. If you buy leads from affiliates or third-party marketers, know what ad or mailer the consumer actually saw before they reached you — a lead isn’t “clean” just because it arrived in your CRM.
Run this review any time you launch a new campaign or bring on a new lead source, and keep records of the actual creative, scripts, and call samples reviewed — that evidence is what will let you show regulators (or yourself) exactly what consumers saw and heard.
For operational guidance and structured compliance documentation tools, visit the CLIClaw Marketing Compliance Library.
© 2026 CLIClaw.com
This article is for information purposes only. It is not intended to be and should not be relied on as legal advice for any particular matter.